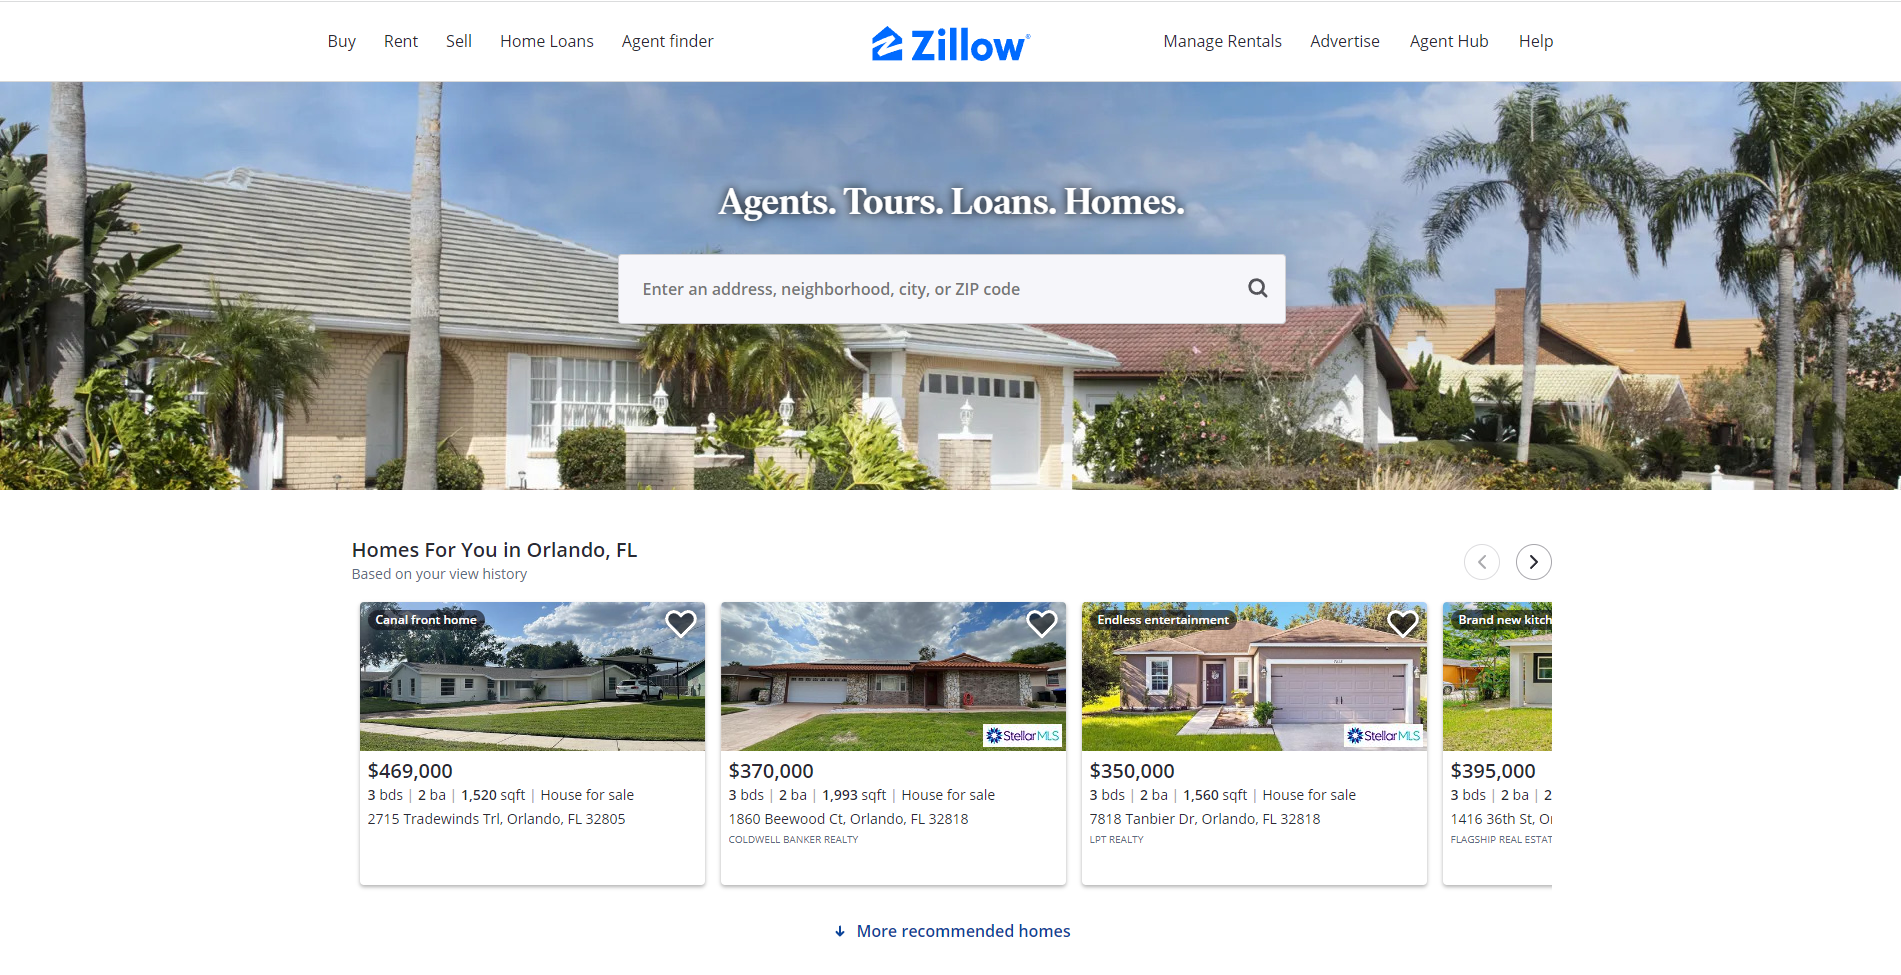
Every week I talk to homeowners who tell me what Zillow says their home is worth. Most of the time that number is higher than what the market will actually support — and most of the time the homeowner is more attached to it than they’d like to admit.
Automated Valuation Models — AVMs, Zestimates, Redfin Estimates — are useful tools for getting a general ballpark quickly. They’re not useful as a pricing strategy for your home. Here’s why, and what to use instead.
An Automated Valuation Model is a software-generated estimate of a property’s value based on publicly available data — tax records, recent sales, square footage, lot size, and historical price trends. It runs an algorithm against that data and produces a number. It does this instantly, at scale, for millions of properties simultaneously.
The Zillow Zestimate is the most widely known AVM. Redfin has its own. Most real estate portals have some version of one. Banks use proprietary AVMs for portfolio valuations and mortgage risk assessment. They’re legitimate tools with real uses — just not the uses most homeowners apply them to.
What an AVM cannot do: enter your home, see the kitchen you renovated, observe that the neighbor’s property backs up to a retention pond, notice the road noise from SR-417, account for the CDD assessment, or know that your street’s last three sales were all distressed. It works from a data set. The data set is incomplete.
Zillow publishes its own accuracy data. For on-market homes — where the listing price is available and feeds into the model — the median error rate is around 2-3%. That sounds reassuring until you do the math. On a $450,000 home, a 2.5% error is $11,250 in either direction. That’s a meaningful number in a real negotiation.
For off-market homes — homes not currently listed, which is the situation when most homeowners check their Zestimate — the error rate is substantially higher. Zillow’s own data shows median error rates for off-market homes running closer to 6-7%. On a $450,000 home that’s a potential swing of $27,000 to $31,500. That’s not a rounding error. That’s a pricing strategy gone wrong.
The error rates also vary significantly by geography. AVMs perform best in dense, homogeneous markets with high transaction volume — think tract neighborhoods where every house is essentially the same. They perform worst in heterogeneous markets with a wide variety of property types, lot sizes, ages, and conditions. Central Florida, with its mix of master-planned communities, older neighborhoods, waterfront lots, CDDs, and varied construction vintages, is exactly the kind of market where AVM errors are largest.
The Central Florida market has characteristics that make AVM accuracy particularly unreliable:
CDD assessments. Two homes with identical square footage on the same street can have meaningfully different effective costs depending on whether they’re in a CDD and what the annual assessment is. An AVM has no way to factor this into value accurately.
Lot-specific features. A home backing up to conservation land versus one backing up to another home’s rear yard, or a waterfront lot versus an interior lot — these differences can be worth $30,000 to $80,000+ in certain communities. An AVM doesn’t see this.
New construction competing with resale. When builders are actively selling in your community at specific price points with incentives and rate buydowns, that affects resale values in ways that don’t appear cleanly in AVM data.
Property tax assessed value vs. market value. Florida’s Save Our Homes cap means a seller’s assessed value on their property tax bill may be significantly lower than market value. Some AVM models partially rely on assessed value data, which introduces distortion.
The practical danger of AVMs for sellers isn’t that they exist — it’s that sellers use them to anchor their pricing expectations before consulting anyone with actual local market knowledge. By the time a seller meets with an agent and sees a CMA, they’ve often already decided their home is worth what the Zestimate said. If the CMA comes in lower, the seller’s first instinct is to question the agent rather than the algorithm.
This anchoring effect leads to overpriced listings. Overpriced listings sit. Listings that sit accumulate days on market, attract attention for the wrong reasons, and typically end up selling for less than they would have if they’d been priced correctly from the start. The data on this is consistent: homes that require price reductions after sitting on market sell at a discount compared to correctly priced homes.
The Zestimate didn’t cause this — the anchoring did. The fix is simple: use the AVM as a rough orientation, then get a CMA from an agent who has physically walked comparable homes in your specific market and can show you what they actually sold for, adjusted for the differences between those homes and yours.
A Comparative Market Analysis — CMA — is what an agent uses to establish a recommended list price. It pulls recent closed sales of comparable homes in your area, makes adjustments for differences in size, condition, features, and location, and arrives at a supportable value range based on what buyers have actually paid for similar homes in the recent market.
The difference from an AVM isn’t just methodology — it’s the judgment layer. An agent preparing a CMA knows that the comp two streets over has a pool and yours doesn’t. They know that a particular subdivision has a higher-than-average CDD assessment that affects buyer demand. They’ve been inside the homes they’re using as comparables and can speak to condition differences that a data model can’t see.
A CMA is free. Any listing consultation should include one. If you want to know what your home is worth in the current Central Florida market — not what an algorithm thinks based on incomplete public data — that’s the right tool.
Want to know what your home is actually worth in today’s Central Florida market? Request a free CMA. No algorithm involved — just a real analysis of what comparable homes are selling for right now.


Leave a Reply